

Ally: Bank, Auto & Invest
by Ally Financial
4.4
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.4
- Price
- Free
- Download
- 1.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
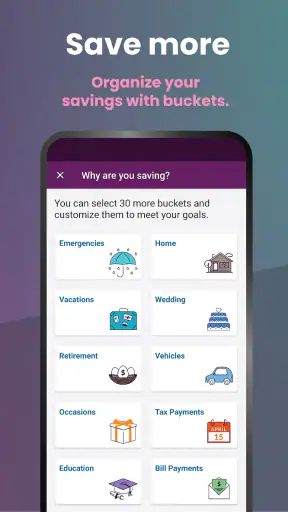
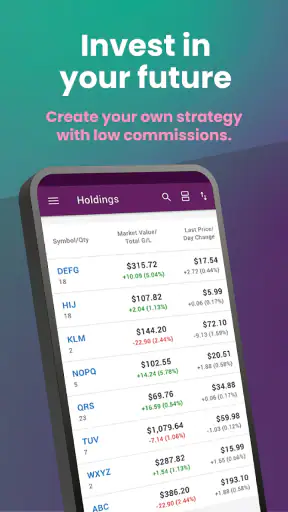
 Analysis by Getfullapps
Managing money from a phone sounds simple until the app becomes the place where you check a balance, move funds, review a purchase, and make a decision while you are away from a computer. Ally: Bank, Auto & Invest is designed around that kind of everyday finance routine. I found it most useful when I treated it as a mobile control panel rather than a complete replacement for every financial tool I use.
Developed by Ally Financial, this free finance app brings banking, auto-related account access, and investing into one mobile experience. Its broad scope is its main appeal, but it also means the quality of the experience depends heavily on your connection, your account relationship with Ally, and how much financial detail you expect from a phone screen. With a 4.4 average from around 41 thousand ratings and over 1 million installs, it is clearly an established option rather than a little-known utility.
How Ally feels when your finances depend on a connection
The first thing I noticed is that the app makes network access part of nearly every meaningful action. Opening the app may feel quick, but checking current account information, reviewing recent activity, moving money, or working with investment information requires the service to communicate with Ally. That is normal for a financial app, yet it changes how you should use it: the phone is the interface, while the important work happens through a live connection.
This matters in ordinary situations. Imagine standing in a shop and wondering whether a purchase will fit your budget. A banking app can help, but only if the balance and recent transactions load when you need them. With Ally, I would avoid treating a screen that has not refreshed as a final answer. If reception is weak, a loading state or an outdated view can turn a two-second check into uncertainty. My practical habit is to open the app before reaching the checkout, while the connection is stable, rather than waiting until the last moment.
The same principle applies to transfers. A transfer is not just a note on the screen; it is an instruction that needs to reach the financial institution and return a confirmation. If the connection drops during that process, I would not immediately repeat the action. I would first reconnect, reopen the relevant area, and check the activity or transfer status. That small pause can help prevent confusion about whether an instruction was accepted.
For financial actions, a visible confirmation is more useful than a fast tap. I recommend waiting for the app to finish loading and keeping any confirmation details until you are sure the transaction appears as expected. This is especially important when you are moving money between accounts or making a payment-related decision under time pressure.
Connectivity also affects investing in a different way. Market information is time-sensitive, so a screen that has not updated should not be treated as a live picture of what is happening. I see this app as convenient for checking an investment position or handling routine account tasks, but not as a reason to make rushed decisions from a weak signal. If the information looks stale, reconnect first and consider whether the decision can wait.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
Useful on the move, but not equally comfortable everywhere
The mobile format suits people who check their money in short sessions. I can imagine using it during a commute, before paying a bill, after filling up a car, or while comparing a planned purchase with the available balance. The app’s combination of banking, auto, and investing makes it particularly relevant to someone who already keeps several parts of their financial life with Ally.
That range is also where the app can feel more demanding than a single-purpose banking tool. A person who only wants to see a checking balance may find the wider financial scope unnecessary. On the other hand, someone who has Ally banking, auto financing, and investment activity may appreciate not having to remember several unrelated apps or websites. The value comes from consolidation, not from any one screen.
On a small phone, financial information can require more attention than it would on a desktop. I prefer using a quiet moment for anything that involves comparing figures, reviewing activity, or deciding whether to move money. Quick checks are fine while standing in line, but detailed financial review is easier when I am not distracted by traffic, conversation, or a low battery.
Car-related use is a good example of the app’s practical reach. If I wanted to review an auto account while away from home, having that information alongside banking access would be convenient. Yet a mobile screen is not the best place to rush through a complicated decision. I would use the app to retrieve current information and begin the task, then take more time if the situation involved a significant financial commitment.
The app is available for users on a supported device running iOS 10 or later, and its current version is 26.14.0. That makes it worth checking your phone’s software before planning to rely on it. Compatibility is easy to overlook when an app is already familiar, especially if an older phone has been kept for travel or as a backup.
What happens when loading fails
Financial apps have a higher recovery standard than ordinary entertainment apps. If a video fails to load, I can try again without much concern. If a transfer screen fails halfway through, I need to know what happened before touching the button again. Ally is therefore best used with a deliberate recovery routine: check the connection, wait briefly, reopen the app, and inspect the account activity before repeating an action.
I would also avoid switching repeatedly between Wi-Fi and mobile data during a sensitive task. A changing connection can make it harder to tell whether a page is merely slow or whether an action actually completed. If I am in a basement, elevator, parking structure, or crowded venue, I would postpone non-urgent money movement and use the app later from a more reliable location.
There is a useful distinction between viewing and acting. If a balance page will not load, the problem is inconvenient. If a payment or transfer is involved, the priority becomes avoiding duplication. This is one of the less obvious habits that makes a mobile banking app safer to use: when a financial action appears interrupted, verify its status before attempting it again.
Recovery is also easier when you keep your phone’s basic conditions in mind. A nearly empty battery, aggressive data-saving settings, or a crowded public network can all make a mobile session less dependable. I would not call these defects unique to Ally, but they are real parts of using it away from a desk. The app can be capable while the surrounding conditions remain unreliable.
For urgent support or a complex account question, the app should not be your only plan. A phone interface is excellent for access and routine control, but a complicated issue may be easier to understand through a fuller support channel or a larger screen. I see the app as the first place to inspect what is happening, not automatically the best place to resolve every unusual case.
Using it without wasting data or attention
Because the experience is connected, I would use it thoughtfully on mobile data. Routine balance checks are usually short, but repeatedly refreshing pages when reception is poor is not a good workflow. It can waste time, use unnecessary data, and still leave you unsure whether the information is current. One deliberate refresh from a stable connection is better than tapping repeatedly.
I also recommend separating low-risk browsing from important actions. If I am simply reviewing recent spending, I can do that during a quick mobile session. If I need to transfer money or inspect an investment position before making a decision, I would wait until I have a dependable connection and enough privacy to read the details properly. This approach is less about saving data alone and more about reducing mistakes.
Privacy is another mobile consideration. A financial screen can reveal balances, transactions, auto information, or investment details at a glance. I would avoid opening it where people can easily see the display, particularly when using public Wi-Fi or handing the phone to someone else. The app’s convenience makes it easy to check money anywhere, but convenience should not remove basic caution.
Notifications and frequent checking can also shape your habits, although the app’s usefulness does not require constant attention. I prefer opening it with a specific purpose: confirm a balance, review activity, check an account, or complete a planned task. That keeps the app from becoming a source of anxious refreshing, especially for investments where short-term changes can encourage impulsive reactions.
A practical workflow is to use a stable connection for a focused review, note what needs action, and complete only the necessary steps. For example, after noticing an unfamiliar purchase, I would first review the transaction details, avoid making assumptions from a partial load, and then decide what follow-up is appropriate. The app is most helpful when it gives structure to that process rather than encouraging hurried taps.
Who will get the most from Ally
I think the strongest audience is an Ally customer who wants one mobile destination for more than basic banking. The combination of bank, auto, and investment access can reduce the friction of switching between separate services. If your financial life is already centered on Ally, the app has a clear practical advantage: it puts related information close together when you are away from a computer.
It is also a sensible choice for people who prefer self-service account management and regularly use a phone for financial checks. The free price removes a direct cost barrier, and the Everyone age rating makes it broadly accessible from a store-classification perspective. Still, access to the app does not mean every person will find every section relevant. A teenager looking only for a simple spending view, or someone who does not use Ally products, may gain less from its wider design.
I would be more cautious about recommending it as the only financial tool for someone who needs intensive budgeting, detailed household planning, or advanced investment analysis. A dedicated budgeting app may provide stronger cross-institution spending organization, while a specialized investment platform may be better for users who need deeper research and trading-focused workflows. Ally’s advantage is the connected relationship between its financial areas, not necessarily maximum depth in every one.
It may also be a poor fit for someone who frequently works in places with unreliable reception and expects to complete important tasks there. The app’s central actions depend on current communication with the service. If your normal routine involves remote travel, underground work, or limited mobile access, plan your non-urgent tasks around a reliable connection instead of assuming the phone will always be ready at the exact moment you need it.
How it compares with familiar alternatives
Compared with a traditional bank website, a dedicated mobile app is more convenient for quick checks and short actions. I do not need to sit at a desk to see what is happening in an account. The trade-off is that a smaller display can make careful review less comfortable, and the phone experience is more exposed to signal problems, battery limits, and distractions.
Compared with a basic banking app, Ally stands out through its broader financial focus. Auto and investment access can make it more useful for an existing Ally customer than a narrow checking-and-savings application. The compromise is that the interface has more to organize. Someone who wants only a minimal banking dashboard may prefer a simpler app, even if it offers fewer connected services.
Compared with a standalone budgeting application, Ally is closer to the source of the account relationship. That can make it the better place to confirm current account information and handle account-specific tasks. A budgeting tool may still be preferable for someone who wants to combine accounts from several institutions or study spending patterns across a household. I would use Ally for direct account control and another category of tool when broader financial planning is the priority.
Compared with a specialized investing app, Ally’s appeal is convenience for people who want investing alongside banking and auto information. A specialist may feel more focused to an active investor, while Ally can feel more coherent to someone managing several financial needs in one place. The right choice depends on whether breadth or investment depth matters more to you.
My final view on staying connected
After using Ally as a mobile finance hub, I see it as a practical choice for customers who want banking, auto, and investing access tied together through one app. Its strongest moments are ordinary ones: checking before a purchase, reviewing activity after a transaction, looking at an account while traveling, or handling a planned task without opening a desktop browser.
The important qualification is connectivity. This is not an app I would use casually during a weak signal and then assume every screen is current. I would give important actions time to confirm, avoid repeating interrupted transfers, and reserve detailed financial decisions for a private place with a dependable connection. Those habits make the experience more predictable and protect against the most frustrating mobile mistakes.
Ally Financial has built a free finance app that is broad enough to serve customers with several types of accounts, while remaining approachable for everyday checks. It is not automatically the best substitute for a dedicated budget planner, a specialist investment platform, or a full desktop session. But if your financial relationship is already with Ally and you want convenient mobile access, I find the combination worthwhile.
For me, the final verdict is straightforward: choose it for connected account access and mobile convenience, not for offline independence or highly specialized analysis. Used with a stable connection and a careful confirmation habit, it can make routine money management much easier. Used in a rush, with poor reception, or as the only tool for every financial need, its limits become much more noticeable. Its best feature is the way it brings several Ally services into one reachable place; its main weakness is that the usefulness of that place depends on being properly connected.
Pros
- Clear overview of checking, savings, credit, and investment accounts
- Mobile check deposit makes adding funds convenient
- Customizable alerts help track balances and account activity
- Ally offers 24/7 customer support through several contact options
- No monthly maintenance fees on many core banking accounts
Cons
- Some features require separate Ally accounts or eligibility requirements
- Investment tools may feel limited for experienced traders
- Cash deposits are not supported at physical retail locations
- Transfers to external banks can take several business days
- App performance may vary during maintenance or high-traffic periods
FAQs for Ally: Bank, Auto & Invest
What is Ally: Bank, Auto & Invest, and what can I use it for?
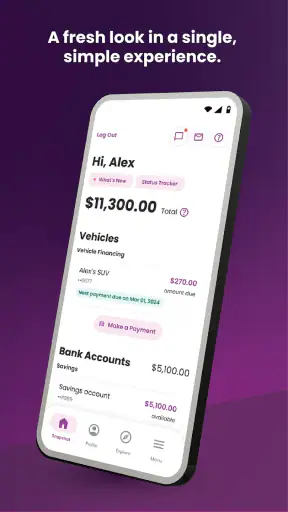
Ally: Bank, Auto & Invest is a mobile app that brings several Ally financial services together in one place. Depending on your eligibility and account type, you can manage checking and savings accounts, transfer money, deposit checks, pay bills, view spending activity, handle auto financing, and monitor eligible investment accounts. The available features may vary by product and customer status.
Is Ally: Bank, Auto & Invest safe to use on a phone?
The app includes standard security features designed to help protect your financial information, such as encrypted connections, login verification, account alerts, and biometric access on supported devices. However, no banking app can eliminate every risk. You should keep your phone and operating system updated, use a strong unique password, avoid public Wi-Fi for sensitive activity, and contact Ally promptly if you notice suspicious transactions or login attempts.
Can I open an Ally bank account directly from the app?
In many cases, new customers can begin applying for eligible Ally products through the app or Ally’s official website. The application may require personal identification details, employment or income information, and verification of your identity. Approval is not guaranteed, and product availability, minimum requirements, interest rates, and account terms can change. Review the current disclosures carefully before submitting an application.
What banking and money-management features are available in the app?
For eligible Ally banking customers, the app may allow you to check balances, review transactions, transfer funds, deposit checks with your camera, send money through supported services, manage bill payments, and receive account notifications. It can also help you organize finances by displaying activity across linked Ally products. Some transfers, deposits, and services may have limits, processing times, or eligibility conditions.
Does the app support Ally Auto and Ally Invest accounts?
The app is designed to provide access to more than traditional banking, including eligible Ally Auto and Ally Invest services. Auto customers may be able to view loan information, payment details, and due dates, while investment customers can review portfolios and manage supported accounts. Features differ by product, account type, and location, and investment values can rise or fall, so the app should not be treated as financial advice.

Ally: Bank, Auto & Invest
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via feedback@ally.com, visit https://www.ally.com/contact-us/, or review their https://www.ally.com/privacy/.










